
Commentary: Trump’s fraudulent war on fraud
For 15 years, I worked in financial regulation and consumer protection, most of that time at the Conference of State Bank Supervisors. My job involved bringing Republican and Democratic state regulators together to go after payday lenders who were writing loans engineered never to be repaid and debt collectors chasing debts that did not exist. It was slow, technical work, and politics rarely ...
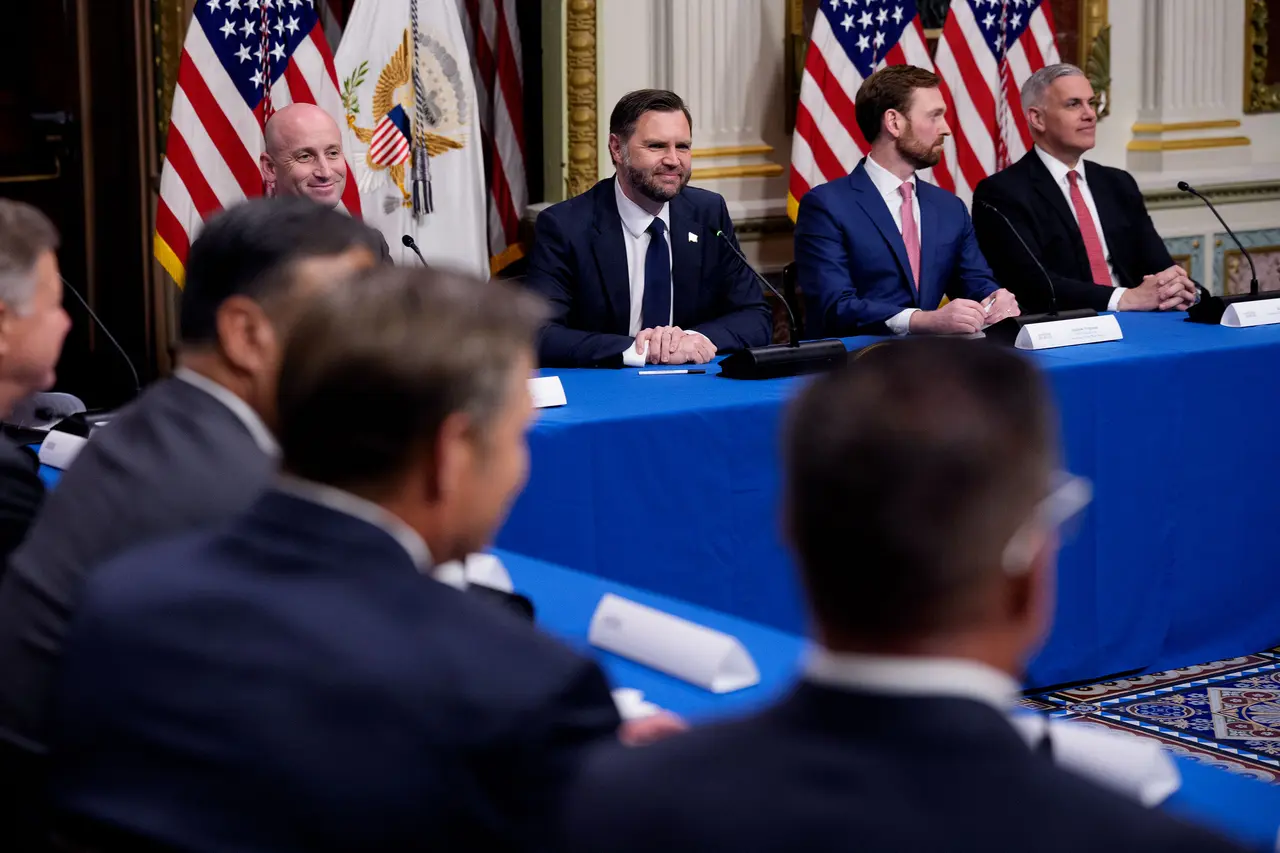
From top left, White House Deputy Chief of Staff and Homeland Security Advisor Stephen Miller, U.S. Vice President JD Vance, Federal Trade Commission Chair Andrew Ferguson, and White House Task Force to Eliminate Fraud Executive Director Scott Brady, appear during a roundtable discussion in the Eisenhower Executive Office Building on the White House Campus...
Andrew Harnik/Getty Images North America/TNS
For 15 years, I worked in financial regulation and consumer protection, most of that time at the Conference of State Bank Supervisors. My job involved bringing Republican and Democratic state regulators together to go after payday lenders who were writing loans engineered never to be repaid and debt collectors chasing debts that did not exist.
It was slow, technical work, and politics rarely mattered. That’s why I have a hard time taking the Trump administration’s new campaign against fraud very seriously.
In March, President Donald Trump created the Task Force to Eliminate Fraud, chaired by Vice President JD Vance. Its attention has largely focused on fraud involving Medicaid, nutrition assistance and other federal benefits. Those crimes should be prosecuted, but they represent only one piece of the problem. The administration has shown considerably less interest in misconduct by people and companies with money and political influence.
Look at what has happened to the Consumer Financial Protection Bureau. Since its founding in 2010, CFPB has returned more than $21 billion to Americans in monetary compensation, principal reductions, canceled debts and other consumer relief.
Shortly after Trump took office, his administration filed a plan to reduce the size of its workforce from about 1,750 people to 556. Supervision was slated for an 85% reduction and enforcement for an 80% reduction. The administration has also permanently dismissed 22 pending enforcement actions and terminated 10 consent orders producing refunds for consumers.
Trump also fired 19 inspectors general, the independent watchdogs responsible for uncovering fraud, waste and abuse throughout the federal government. More than 75% of presidentially appointed inspector general positions are now vacant. These offices collectively identified more than $70 billion in potential savings in fiscal 2024 alone.
On Aug. 11, the Treasury Department’s Financial Crimes Enforcement Network permanently ended the requirement that U.S. companies disclose who actually owns them. It also plans to delete from its database the ownership information that companies have already reported.
Having spent years working around financial enforcement, I cannot understand how deleting information about who owns a company helps investigate fraud. Determining who ultimately controls an entity is often essential to following the money.
Republicans in Congress have spent months talking about fraud as a major legislative priority. Yet their latest reconciliation package contained none of the fraud provisions they had discussed. They now say they plan to address the issue after the November elections.
If this is as urgent an issue as the administration says, there is no reason to wait until voters have cast their ballots. Republicans control the government and could act now.
The administration’s approach is especially difficult to accept while Trump personally benefits from financial ventures that smack of insider dealing. Forbes valued his fortune at roughly $2.3 billion when he returned to office in January 2025, and now estimates it at about $6.5 billion — with crypto ventures accounting for some $3 billion of that increase.
I know from my experience in this area that when a trusted name lends credibility to an asset with little underlying value, excitement drives ordinary investors to buy in; this can lead to huge gains (however undeservedly) for the trusted name and huge losses for the ordinary investors.
Vance should appreciate the consequences when economic systems favor people with power. He became nationally known by writing about communities devastated by economic forces beyond their control. Yet the fraud initiative he chairs concentrates on government benefits while the administration weakens institutions that are responsible for policing misconduct in the financial system.
Real fraud enforcement requires investigators, subpoena power, restitution for victims, accurate ownership information and independent inspectors general. It also requires a willingness to investigate people who have money, influence and expensive lawyers.
Anti-fraud efforts, I believe, should be judged on the basis of the investigators it employs, the cases it brings, the money it returns to victims and whether the same rules apply to everyone. Using those measures, the Trump administration has a lot to explain.
____
Dan Schwartz, former Senior Director of Non-Bank Supervision & Enforcement at the Conference of State Bank Supervisors, is the Democratic nominee for Congress in Maryland’s First District. This column was produced for Progressive Perspectives, a project of The Progressive magazine, and distributed by Tribune News Service.
_____